Net Worth Tiers โ€” 2026 Edition

Jason Voorhees

Jason Voorhees

๐•ธ๐–Š๐–—๐–ˆ๐–Š๐–“๐–†๐–—๐–ž ๐•ฎ๐–”๐–—๐–• โ€ข ๐Ÿ๐ŸŽ๐Ÿ๐Ÿ’๐Ÿฅ‡
Joined
May 15, 2020
Posts
97,153
Reputation
295,615
Net Worth Tiers โ€” 2026 Edition

I updated my old wealth-tier system for 2026. This time I'm accounting for inflation, housing costs, purchasing power, and the fact that $1M at 25 and $1M at 65 are two completely different situations.

1. ๐Ÿ’€ Debt-Bound โ€” < $0 NW

Your liabilities exceed your assets. Debt is eating into your income and you have little/no financial cushion and are dependent on your parents or someone directly. The government gives you zero love here. Consumer debts like credit cards, personal loans offers $0 in tax deductions. You are treated and are by all means a financial leper

Goal: Kill high-interest debt, establish liquidity and reach $0.

Honestly a terrible situation to be at any age unless you are in school but especially worse if you're approaching 20+ with substantial negative net worth.

2. Financially Struggling โ€” $0โ€“$65K

Positive net worth, but not much financial resilience. A job loss, medical emergency can bring you to the streets. You can't afford legal loopholes, so your best play is tax deferral and tax advantaged accounts of your country like Roth IRA, 401k etc. Claim the Saver's Match/Credit if eligible and other government schemes available

Goal: 3โ€“6 months emergency fund + start investing.

18โ€“25: Fine. You're just starting.
25โ€“35: Bad situation but okay start building aggressively
35โ€“45: Falling behind
45+: ๐Ÿšจ You have failed at life

3. Financially Stable โ€” $65Kโ€“$150K

You have manageable debt and consistent positive cash flow. No longer financially fragile, but you're still heavily dependent on employment. Your primary tax shield is maxing out tax advantaged accounts. More of them open to you since you are financially stable example for USA like HSA for and Backdoor Roth IRAs.

Goal: Build a substantial investment portfolio and start approaching true financial independence.

20โ€“25: Good
25โ€“35: Not bad
35โ€“45: Bad
45+: Failed at life

4. Core Middle Class โ€” $150Kโ€“$1.2M

In 2026. Comfortable or barely Millionaire is middle class in most US cities unless you live in middle of nowhere . It's simply a reality whether you want to accept it or not. Overall solid accumulated wealth. Can start a family have a retirement accounts, investments, home equity and other assets. Same strategy as tiers below but with a lot more leeway and investment potential. Also in the weird twilight zone of wealth too poor for loopholes,too rich for benefits. Also called the middle class squeeze

You can have a comfortable conventional lifestyle vacations, decent cars, homeownership but you're not financially bulletproof yet.

Goal: Build enough assets so you no longer need a job eventually

Age verdict:

20โ€“25: Very Good
25โ€“35: Good
35โ€“45: Decent
45โ€“50: Fine
55+: Okay but you still probably need more assets to retire.

5. Affluent / Upper-Middle โ€” $1.2Mโ€“$6M

You are a millionaire at $1M+, although $1.2M and $6M obviously produce very different lifestyles. In a low/mid-cost region financial independence can become realistic. In New York, London, San Francisco, Singapore and other expensive hubs the same money is pretty much middle class. The shift from ordinary income to capital gains begins now for harvesting long-term capital gains so you can do proper wealth building instead of fighting for scraps now

Goal: Transition from earning money to building assets and wealth to produce your lifestyle.

Age verdict:

20โ€“25: Baller
25โ€“35: Exceptional.
35โ€“45: Excellent.
45โ€“55: Great
55+: Wealthy, although retirement spending and asset liquidity matter.


6. High Net Worth โ€” $6Mโ€“$15M

Now we are talking about real wealth. You are in genuine financial independence territory. Can potentially generate a very substantial income from investments if you play your cards well. All the lucrative investment options open up. The biggest enemy at this tier and after this will be taxes so your priority would be to minimize the money you give to government. So after this tier it is a balancing act. You need to Master Buy, Borrow, Die. Borrow low-interest funds against portfolio lines of credit to fund lifestyle tax-free while going into exchanges to roll over real estate gains indefinitely.

Luxury housing, premium vehicles, international travel and expensive hobbies everything within reach

Goal: Optimize taxes this is the most important goal, Diversify and generate sustainable investment income and learn about tax loopholes, hedging and other grey area tactics

Age verdict:

20โ€“30: Filthy
30โ€“40: Exceptional
40โ€“50: Excellent.
50โ€“60: Very wealthy.
60+: You have substantial retirement/legacy wealth.


7. Very High Net Worth โ€” $15Mโ€“$50M

At this point your lifestyle is largely detached from employment. You are not the one getting a 6 figure salary you are the one paying people 6 figure salaries. Once again the biggest enemy is taxes, liabilities, policies. It is less about how do I earn more money and more of how do I protect the money I already have because taxes will rape your ass if you are not careful

Multiple homes, luxury vehicles, extensive international travel and substantial private market investments are all realistic.

At this tier. You should have a family office style wealth management and permanently employ people to move capital and make investments for you to protect your wealth. Hire specialised CPAs and attorneys to deploy Irrevocable Trusts to shield your millions from the IRS

Goal: Estate planning, asset protection, intergenerational wealth and capital allocation by employing a group of wealth managers and accountants.

Under 30: What the hell are you doing nigga
30โ€“40: Extremely rare.
40โ€“50: Elite wealth.
50โ€“60: Exceptionally wealthy.
60+: Massive legacy potential.

8. Ultra-High Net Worth โ€” $50Mโ€“$500M

You're now in the global wealth elite. Netflix movie tier rich. Rich to the point of having so much that you can't even spend it all alone. Rich enough to influence elections, change policies etc also.

Private aircraft, superyachts, multiple international properties and large private-company investments are financially accessible.

At this scale, ordinary consumption barely moves the balance sheet. To protect your wealth you need to operate like an institution. Offshore Holding Structures, Captive Insurance companies, Opportunity Zone funds around the globe. Lot of ways of avoiding taxes when you are this rich with good connections and a network

Goal: Preserve and compound capital, control major assets/businesses, institutionalize wealth and create lasting legacy.

Age verdict:

Under 40: You have basically broken the game. ๐Ÿ—ฟ
40โ€“50: Extremely exceptional.
50โ€“70: Elite global wealth.
70+: The question is now what happens to the wealth after you.

Note: $30M+ is commonly used as the industry UHNW threshold but I'm using $50M here to create a cleaner lifestyle tier.


9. Billionaire / Near-Billionaire โ€” $500Mโ€“$100B

$500M isn't technically billionaire territory hence the near-billionaire label. At $1B+, personal consumption is no longer the interesting part. You can't spend that money even if you want to on material assets. The important thing is ownership.

You may own a major corporation, enormous equity positions or businesses whose activities affect entire industries. Funnily enough at this tier of wealth your effective income tax rate is ironically lower than your assistant because net worths at this tier lives in unrealized stock/equity. Draw $1 salaries, take massive loans against equity, and dump large share blocks into Charitable Lead/Remainder Trusts (CLATs/CRUTs) and avoid taxes entirely but still have the ability to vote and have complete autonomy and power. Like the old saying goes it is very expensive to be poor
Images


Goal: Corporate control, capital allocation, global expansion, philanthropy and legacy.

Age verdict:

Under 40: You are an extreme statistical outlier.
40โ€“60: Usually the result of extraordinary entrepreneurship. Obviously extremely rich
60+: Still an extraordinarily rare level of wealth.

10. ๐Ÿ‘‘ Centibillionaire โ€” $100B+

This is another universe. At this point, the distinction between rich and extremely rich becomes almost meaningless. You're dealing with fortunes large enough that market fluctuations can change your net worth by $5B in a single afternoon. Can buy anything and everything possible.

You don't adapt to tax codes. Tax codes adapt to you. You have direct access to world leaders who are ready the lick the sole of your boots to appease your company and make you happy. You can directly negotiate custom sovereign level corporate tax just for you and so much more. you are practically an emperor in the modern world

Goal: Shape human progress, fund space programs, build AI networks, and influence geopolitical policy.

Age verdict:

Any age: ๐Ÿ—ฟ You're one of the wealthiest humans in recorded history.

You can adapt the above numbers for your country by multiplying the ranges with the PPP of your country to get a rough idea if you are not from the US


Also net worth is only one dimension.

Age + location + liquidity + income + spending = actual financial position.

Which tier are you in? Comment below.
 
Last edited:
  • +1
  • JFL
  • So Sad
Reactions: HispanicMogger, ร˜UROBOROS, Sayori and 22 others
@BigBallsLarry @imontheloose @Chadeep @buccalfatremoval
 
  • +1
Reactions: socio, hopelessmanlet32, BigBallsLarry and 1 other person
@Mast @Joeseminate @Rabbi @BeanCelll @optimisticzoomer
 
  • +1
Reactions: Joeseminate, hopelessmanlet32, zennn and 1 other person
i got 230 bucks at 17 is that good
 
  • +1
Reactions: hopelessmanlet32, Vrilltrum, Askinov and 3 others
@Askinov @romanstock @Yliaster @Daddy's Home @Gargantuan
 
  • +1
Reactions: Askinov and zennn
40k at 36, richest on this forum.
 
  • +1
  • So Sad
  • Woah
Reactions: ร˜UROBOROS, hopelessmanlet32, Vrilltrum and 3 others
Net Worth Tiers โ€” 2026 Edition

I updated my old wealth-tier system for 2026. This time I'm accounting for inflation, housing costs, purchasing power, and the fact that $1M at 25 and $1M at 65 are two completely different situations.

1. ๐Ÿ’€ Debt-Bound โ€” < $0 NW

Your liabilities exceed your assets. Debt is eating into your income and you have little/no financial cushion and are dependent on your parents or someone directly. The government gives you zero love here. Consumer debts like credit cards, personal loans offers $0 in tax deductions. You are treated and are by all means a financial leper

Goal: Kill high-interest debt, establish liquidity and reach $0.

Honestly a terrible situation to be at any age unless you are in school but especially worse if you're approaching 20+ with substantial negative net worth.

2. Financially Struggling โ€” $0โ€“$65K

Positive net worth, but not much financial resilience. A job loss, medical emergency can bring you to the streets. You can't afford legal loopholes, so your best play is tax deferral and tax advantaged accounts of your country like Roth IRA, 401k etc. Claim the Saver's Match/Credit if eligible and other government schemes available

Goal: 3โ€“6 months emergency fund + start investing.

18โ€“25: Fine. You're just starting.
25โ€“35: Bad situation but okay start building aggressively
35โ€“45: Falling behind
45+: ๐Ÿšจ You have failed at life

3. Financially Stable โ€” $65Kโ€“$150K

You have manageable debt and consistent positive cash flow. No longer financially fragile, but you're still heavily dependent on employment. Your primary tax shield is maxing out tax advantaged accounts. More of them open to you since you are financially stable example for USA like HSA for and Backdoor Roth IRAs.

Goal: Build a substantial investment portfolio and start approaching true financial independence.

20โ€“25: Good
25โ€“35: Not bad
35โ€“45: Bad
45+: Failed at life

4. Core Middle Class โ€” $150Kโ€“$1.2M

In 2026. Comfortable or barely Millionaire is middle class in most US cities unless you live in middle of nowhere . It's simply a reality whether you want to accept it or not. Overall solid accumulated wealth. Can start a family have a retirement accounts, investments, home equity and other assets. Same strategy as tiers below but with a lot more leeway and investment potential. Also in the weird twilight zone of wealth too poor for loopholes,too rich for benefits. Also called the middle class squeeze

You can have a comfortable conventional lifestyle vacations, decent cars, homeownership but you're not financially bulletproof yet.

Goal: Build enough assets so you no longer need a job eventually

Age verdict:

20โ€“25: Very Good
25โ€“35: Good
35โ€“45: Decent
45โ€“50: Fine
55+: Okay but you still probably need more assets to retire.

5. Affluent / Upper-Middle โ€” $1.2Mโ€“$6M

You are a millionaire at $1M+, although $1.2M and $6M obviously produce very different lifestyles. In a low/mid-cost region financial independence can become realistic. In New York, London, San Francisco, Singapore and other expensive hubs the same money is pretty much middle class. The shift from ordinary income to capital gains begins now for harvesting long-term capital gains so you can do proper wealth building instead of fighting for scraps now

Goal: Transition from earning money to building assets and wealth to produce your lifestyle.

Age verdict:

20โ€“25: Baller
25โ€“35: Exceptional.
35โ€“45: Excellent.
45โ€“55: Great
55+: Wealthy, although retirement spending and asset liquidity matter.


6. High Net Worth โ€” $6Mโ€“$15M

Now we are talking about real wealth. You are in genuine financial independence territory. Can potentially generate a very substantial income from investments if you play your cards well. All the lucrative investment options open. The biggest enemy at this tier and after this will be taxes so your priority would be to minimize the money you give to government. So after this tier it is a balancing act. You need to Master Buy, Borrow, Die. Borrow low-interest funds against portfolio lines of credit to fund lifestyle tax-free while going into exchanges to roll over real estate gains indefinitely.

Luxury housing, premium vehicles, international travel and expensive hobbies everything within reach

Goal: Optimize taxes this is the most important goal, Diversify and generate sustainable investment income and don't learn about tax loopholes, hedging and other grey area tactics

Age verdict:

20โ€“30: Filthy
30โ€“40: Exceptional
40โ€“50: Excellent.
50โ€“60: Very wealthy.
60+: You have substantial retirement/legacy wealth.


7. Very High Net Worth โ€” $15Mโ€“$50M

At this point your lifestyle is largely detached from employment. You are not the one getting a 6 figure salary you are the one paying people 6 figures. Once again the biggest enemy is taxes, liabilities, policies. It is less about how do I earn more money and more of how do I protect the money I already have because taxes will rape your ass if you are not careful

Multiple homes, luxury vehicles, extensive international travel and substantial private market investments are all realistic.

At this tier. You should have a family office style wealth management and permanently employ people to move capital and make investments for you to protect your wealth. Hire specialised CPAs and attorneys to deploy Irrevocable Trusts to shield your millions from the IRS

Goal: Estate planning, asset protection, intergenerational wealth and capital allocation by employing a group of wealth managers and accountants.

Under 30: What the hell are you doing nigga
30โ€“40: Extremely rare.
40โ€“50: Elite wealth.
50โ€“60: Exceptionally wealthy.
60+: Massive legacy potential.

8. Ultra-High Net Worth โ€” $50Mโ€“$500M

You're now in the global wealth elite. Netflix movie tier rich. Rich to the point of having so much that you can't even spend it all alone. Rich enough to influence elections, change policies etc also.

Private aircraft, superyachts, multiple international properties and large private-company investments are financially accessible.

At this scale, ordinary consumption barely moves the balance sheet. To protect your wealth you need to operate like an institution. Offshore Holding Structures, Captive Insurance companies, Opportunity Zone funds around the globe. Lot of ways to avoid taxes open up when you are this rich with good connections and a network

Goal: Preserve and compound capital, control major assets/businesses, institutionalize wealth and create lasting legacy.

Age verdict:

Under 40: You have basically broken the game. ๐Ÿ—ฟ
40โ€“50: Extremely exceptional.
50โ€“70: Elite global wealth.
70+: The question is now what happens to the wealth after you.

Note: $30M+ is commonly used as the industry UHNW threshold but I'm using $50M here to create a cleaner lifestyle tier.


9. Billionaire / Near-Billionaire โ€” $500Mโ€“$100B

$500M isn't technically billionaire territory hence the near-billionaire label. At $1B+, personal consumption is no longer the interesting part. You can't spend that money even if you want to on material assets. The important thing is ownership.

You may own a major corporation, enormous equity positions or businesses whose activities affect entire industries. Funnily enough at this tier of wealth your effective income tax rate is ironically lower than your assistant because net worths at this tier lives in unrealized stock/equity. Draw $1 salaries, take massive loans against equity, and dump large share blocks into Charitable Lead/Remainder Trusts (CLATs/CRUTs) and avoid taxes entirely but still have the ability to vote and have complete power. Like the old saying goes it is very expensive to be poor

View attachment 5643186

Goal: Corporate control, capital allocation, global expansion, philanthropy and legacy.

Age verdict:

Under 40: You are an extreme statistical outlier.
40โ€“60: Usually the result of extraordinary entrepreneurship. Obviously extremely rich
60+: Still an extraordinarily rare level of wealth.

10. ๐Ÿ‘‘ Centibillionaire โ€” $100B+

This is another universe. At this point, the distinction between rich and extremely rich becomes almost meaningless. You're dealing with fortunes large enough that market fluctuations can change your net worth by $5B in a single afternoon. Can buy anything and everything possible.

You don't adapt to tax codes. Tax codes adapt to you. You have direct access to world leaders who are ready the lick the sole of your boots to appease your company and make you happy. You can directly negotiate custom sovereign level corporate tax just for you and so much more. you are practically an emperor in the modern world

Goal: Shape human progress, fund space programs, build AI networks, and influence geopolitical policy.

Age verdict:

Any age: ๐Ÿ—ฟ You're one of the wealthiest humans in recorded history.

You can adapt the above numbers for your country by multiplying the ranges with the PPP of your country to get a rough idea if you are not from the US


Also net worth is only one dimension.

Age + location + liquidity + income + spending = actual financial position.

Which tier are you in? Comment below.
This thread is genuinely a breath of fresh air. Very enjoyable and nicely formatted.
 
  • +1
Reactions: ร˜UROBOROS and Jason Voorhees
  • JFL
  • +1
Reactions: HispanicMogger, socio and romanstock
  • +1
  • Love it
Reactions: Askinov and zombi3
  • +1
Reactions: Askinov and AryanSchizo
You are in tier 1. You should aim to get to tier 3-4 by your 40s
Iโ€™ll try. Some dumb foid totalled my car last year which I was at fault for even tho she was rly at fault . Learned a lesson to use a dashcam always.
And rent levels are insane. COL is cooked
 
  • +1
Reactions: Askinov, Jason Voorhees and zennn
800 bucks at 17 nearing out age 18 is it good
 
  • +1
Reactions: Jason Voorhees and zennn
dude i make 750 bucks per month with 42.5 hours per week

im getting fucking robbed
Ur 17 tho u chilling , I was working at whataburger when I was in hs eating their fries n shit lmao
 
  • +1
Reactions: zennn and Jason Voorhees
dude i make 750 bucks per month with 42.5 hours per week

im getting fucking robbed
i get 100โ‚ฌ a month for 40h thats called robbery
 
  • +1
  • JFL
  • So Sad
Reactions: SecularIslamist, zennn and Jason Voorhees
@ewri @sasha108 @SecularIslamist @Former Shortcel
 
  • +1
Reactions: ewri and sasha108
Net Worth Tiers โ€” 2026 Edition

I updated my old wealth-tier system for 2026. This time I'm accounting for inflation, housing costs, purchasing power, and the fact that $1M at 25 and $1M at 65 are two completely different situations.

1. ๐Ÿ’€ Debt-Bound โ€” < $0 NW

Your liabilities exceed your assets. Debt is eating into your income and you have little/no financial cushion and are dependent on your parents or someone directly. The government gives you zero love here. Consumer debts like credit cards, personal loans offers $0 in tax deductions. You are treated and are by all means a financial leper

Goal: Kill high-interest debt, establish liquidity and reach $0.

Honestly a terrible situation to be at any age unless you are in school but especially worse if you're approaching 20+ with substantial negative net worth.

2. Financially Struggling โ€” $0โ€“$65K

Positive net worth, but not much financial resilience. A job loss, medical emergency can bring you to the streets. You can't afford legal loopholes, so your best play is tax deferral and tax advantaged accounts of your country like Roth IRA, 401k etc. Claim the Saver's Match/Credit if eligible and other government schemes available

Goal: 3โ€“6 months emergency fund + start investing.

18โ€“25: Fine. You're just starting.
25โ€“35: Bad situation but okay start building aggressively
35โ€“45: Falling behind
45+: ๐Ÿšจ You have failed at life

3. Financially Stable โ€” $65Kโ€“$150K

You have manageable debt and consistent positive cash flow. No longer financially fragile, but you're still heavily dependent on employment. Your primary tax shield is maxing out tax advantaged accounts. More of them open to you since you are financially stable example for USA like HSA for and Backdoor Roth IRAs.

Goal: Build a substantial investment portfolio and start approaching true financial independence.

20โ€“25: Good
25โ€“35: Not bad
35โ€“45: Bad
45+: Failed at life

4. Core Middle Class โ€” $150Kโ€“$1.2M

In 2026. Comfortable or barely Millionaire is middle class in most US cities unless you live in middle of nowhere . It's simply a reality whether you want to accept it or not. Overall solid accumulated wealth. Can start a family have a retirement accounts, investments, home equity and other assets. Same strategy as tiers below but with a lot more leeway and investment potential. Also in the weird twilight zone of wealth too poor for loopholes,too rich for benefits. Also called the middle class squeeze

You can have a comfortable conventional lifestyle vacations, decent cars, homeownership but you're not financially bulletproof yet.

Goal: Build enough assets so you no longer need a job eventually

Age verdict:

20โ€“25: Very Good
25โ€“35: Good
35โ€“45: Decent
45โ€“50: Fine
55+: Okay but you still probably need more assets to retire.

5. Affluent / Upper-Middle โ€” $1.2Mโ€“$6M

You are a millionaire at $1M+, although $1.2M and $6M obviously produce very different lifestyles. In a low/mid-cost region financial independence can become realistic. In New York, London, San Francisco, Singapore and other expensive hubs the same money is pretty much middle class. The shift from ordinary income to capital gains begins now for harvesting long-term capital gains so you can do proper wealth building instead of fighting for scraps now

Goal: Transition from earning money to building assets and wealth to produce your lifestyle.

Age verdict:

20โ€“25: Baller
25โ€“35: Exceptional.
35โ€“45: Excellent.
45โ€“55: Great
55+: Wealthy, although retirement spending and asset liquidity matter.


6. High Net Worth โ€” $6Mโ€“$15M

Now we are talking about real wealth. You are in genuine financial independence territory. Can potentially generate a very substantial income from investments if you play your cards well. All the lucrative investment options open up. The biggest enemy at this tier and after this will be taxes so your priority would be to minimize the money you give to government. So after this tier it is a balancing act. You need to Master Buy, Borrow, Die. Borrow low-interest funds against portfolio lines of credit to fund lifestyle tax-free while going into exchanges to roll over real estate gains indefinitely.

Luxury housing, premium vehicles, international travel and expensive hobbies everything within reach

Goal: Optimize taxes this is the most important goal, Diversify and generate sustainable investment income and learn about tax loopholes, hedging and other grey area tactics

Age verdict:

20โ€“30: Filthy
30โ€“40: Exceptional
40โ€“50: Excellent.
50โ€“60: Very wealthy.
60+: You have substantial retirement/legacy wealth.


7. Very High Net Worth โ€” $15Mโ€“$50M

At this point your lifestyle is largely detached from employment. You are not the one getting a 6 figure salary you are the one paying people 6 figure salaries. Once again the biggest enemy is taxes, liabilities, policies. It is less about how do I earn more money and more of how do I protect the money I already have because taxes will rape your ass if you are not careful

Multiple homes, luxury vehicles, extensive international travel and substantial private market investments are all realistic.

At this tier. You should have a family office style wealth management and permanently employ people to move capital and make investments for you to protect your wealth. Hire specialised CPAs and attorneys to deploy Irrevocable Trusts to shield your millions from the IRS

Goal: Estate planning, asset protection, intergenerational wealth and capital allocation by employing a group of wealth managers and accountants.

Under 30: What the hell are you doing nigga
30โ€“40: Extremely rare.
40โ€“50: Elite wealth.
50โ€“60: Exceptionally wealthy.
60+: Massive legacy potential.

8. Ultra-High Net Worth โ€” $50Mโ€“$500M

You're now in the global wealth elite. Netflix movie tier rich. Rich to the point of having so much that you can't even spend it all alone. Rich enough to influence elections, change policies etc also.

Private aircraft, superyachts, multiple international properties and large private-company investments are financially accessible.

At this scale, ordinary consumption barely moves the balance sheet. To protect your wealth you need to operate like an institution. Offshore Holding Structures, Captive Insurance companies, Opportunity Zone funds around the globe. Lot of ways of avoiding taxes when you are this rich with good connections and a network

Goal: Preserve and compound capital, control major assets/businesses, institutionalize wealth and create lasting legacy.

Age verdict:

Under 40: You have basically broken the game. ๐Ÿ—ฟ
40โ€“50: Extremely exceptional.
50โ€“70: Elite global wealth.
70+: The question is now what happens to the wealth after you.

Note: $30M+ is commonly used as the industry UHNW threshold but I'm using $50M here to create a cleaner lifestyle tier.


9. Billionaire / Near-Billionaire โ€” $500Mโ€“$100B

$500M isn't technically billionaire territory hence the near-billionaire label. At $1B+, personal consumption is no longer the interesting part. You can't spend that money even if you want to on material assets. The important thing is ownership.

You may own a major corporation, enormous equity positions or businesses whose activities affect entire industries. Funnily enough at this tier of wealth your effective income tax rate is ironically lower than your assistant because net worths at this tier lives in unrealized stock/equity. Draw $1 salaries, take massive loans against equity, and dump large share blocks into Charitable Lead/Remainder Trusts (CLATs/CRUTs) and avoid taxes entirely but still have the ability to vote and have complete autonomy and power. Like the old saying goes it is very expensive to be poor

View attachment 5643186

Goal: Corporate control, capital allocation, global expansion, philanthropy and legacy.

Age verdict:

Under 40: You are an extreme statistical outlier.
40โ€“60: Usually the result of extraordinary entrepreneurship. Obviously extremely rich
60+: Still an extraordinarily rare level of wealth.

10. ๐Ÿ‘‘ Centibillionaire โ€” $100B+

This is another universe. At this point, the distinction between rich and extremely rich becomes almost meaningless. You're dealing with fortunes large enough that market fluctuations can change your net worth by $5B in a single afternoon. Can buy anything and everything possible.

You don't adapt to tax codes. Tax codes adapt to you. You have direct access to world leaders who are ready the lick the sole of your boots to appease your company and make you happy. You can directly negotiate custom sovereign level corporate tax just for you and so much more. you are practically an emperor in the modern world

Goal: Shape human progress, fund space programs, build AI networks, and influence geopolitical policy.

Age verdict:

Any age: ๐Ÿ—ฟ You're one of the wealthiest humans in recorded history.

You can adapt the above numbers for your country by multiplying the ranges with the PPP of your country to get a rough idea if you are not from the US


Also net worth is only one dimension.

Age + location + liquidity + income + spending = actual financial position.

Which tier are you in? Comment below.
read all tho bhai cool thread
 
  • +1
Reactions: AryanSchizo, zennn and Jason Voorhees
@inyerta @WonkyChin186 @theblueprints
 
Net Worth Tiers โ€” 2026 Edition

I updated my old wealth-tier system for 2026. This time I'm accounting for inflation, housing costs, purchasing power, and the fact that $1M at 25 and $1M at 65 are two completely different situations.

1. ๐Ÿ’€ Debt-Bound โ€” < $0 NW

Your liabilities exceed your assets. Debt is eating into your income and you have little/no financial cushion and are dependent on your parents or someone directly. The government gives you zero love here. Consumer debts like credit cards, personal loans offers $0 in tax deductions. You are treated and are by all means a financial leper

Goal: Kill high-interest debt, establish liquidity and reach $0.

Honestly a terrible situation to be at any age unless you are in school but especially worse if you're approaching 20+ with substantial negative net worth.

2. Financially Struggling โ€” $0โ€“$65K

Positive net worth, but not much financial resilience. A job loss, medical emergency can bring you to the streets. You can't afford legal loopholes, so your best play is tax deferral and tax advantaged accounts of your country like Roth IRA, 401k etc. Claim the Saver's Match/Credit if eligible and other government schemes available

Goal: 3โ€“6 months emergency fund + start investing.

18โ€“25: Fine. You're just starting.
25โ€“35: Bad situation but okay start building aggressively
35โ€“45: Falling behind
45+: ๐Ÿšจ You have failed at life

3. Financially Stable โ€” $65Kโ€“$150K

You have manageable debt and consistent positive cash flow. No longer financially fragile, but you're still heavily dependent on employment. Your primary tax shield is maxing out tax advantaged accounts. More of them open to you since you are financially stable example for USA like HSA for and Backdoor Roth IRAs.

Goal: Build a substantial investment portfolio and start approaching true financial independence.

20โ€“25: Good
25โ€“35: Not bad
35โ€“45: Bad
45+: Failed at life

4. Core Middle Class โ€” $150Kโ€“$1.2M

In 2026. Comfortable or barely Millionaire is middle class in most US cities unless you live in middle of nowhere . It's simply a reality whether you want to accept it or not. Overall solid accumulated wealth. Can start a family have a retirement accounts, investments, home equity and other assets. Same strategy as tiers below but with a lot more leeway and investment potential. Also in the weird twilight zone of wealth too poor for loopholes,too rich for benefits. Also called the middle class squeeze

You can have a comfortable conventional lifestyle vacations, decent cars, homeownership but you're not financially bulletproof yet.

Goal: Build enough assets so you no longer need a job eventually

Age verdict:

20โ€“25: Very Good
25โ€“35: Good
35โ€“45: Decent
45โ€“50: Fine
55+: Okay but you still probably need more assets to retire.

5. Affluent / Upper-Middle โ€” $1.2Mโ€“$6M

You are a millionaire at $1M+, although $1.2M and $6M obviously produce very different lifestyles. In a low/mid-cost region financial independence can become realistic. In New York, London, San Francisco, Singapore and other expensive hubs the same money is pretty much middle class. The shift from ordinary income to capital gains begins now for harvesting long-term capital gains so you can do proper wealth building instead of fighting for scraps now

Goal: Transition from earning money to building assets and wealth to produce your lifestyle.

Age verdict:

20โ€“25: Baller
25โ€“35: Exceptional.
35โ€“45: Excellent.
45โ€“55: Great
55+: Wealthy, although retirement spending and asset liquidity matter.


6. High Net Worth โ€” $6Mโ€“$15M

Now we are talking about real wealth. You are in genuine financial independence territory. Can potentially generate a very substantial income from investments if you play your cards well. All the lucrative investment options open up. The biggest enemy at this tier and after this will be taxes so your priority would be to minimize the money you give to government. So after this tier it is a balancing act. You need to Master Buy, Borrow, Die. Borrow low-interest funds against portfolio lines of credit to fund lifestyle tax-free while going into exchanges to roll over real estate gains indefinitely.

Luxury housing, premium vehicles, international travel and expensive hobbies everything within reach

Goal: Optimize taxes this is the most important goal, Diversify and generate sustainable investment income and learn about tax loopholes, hedging and other grey area tactics

Age verdict:

20โ€“30: Filthy
30โ€“40: Exceptional
40โ€“50: Excellent.
50โ€“60: Very wealthy.
60+: You have substantial retirement/legacy wealth.


7. Very High Net Worth โ€” $15Mโ€“$50M

At this point your lifestyle is largely detached from employment. You are not the one getting a 6 figure salary you are the one paying people 6 figure salaries. Once again the biggest enemy is taxes, liabilities, policies. It is less about how do I earn more money and more of how do I protect the money I already have because taxes will rape your ass if you are not careful

Multiple homes, luxury vehicles, extensive international travel and substantial private market investments are all realistic.

At this tier. You should have a family office style wealth management and permanently employ people to move capital and make investments for you to protect your wealth. Hire specialised CPAs and attorneys to deploy Irrevocable Trusts to shield your millions from the IRS

Goal: Estate planning, asset protection, intergenerational wealth and capital allocation by employing a group of wealth managers and accountants.

Under 30: What the hell are you doing nigga
30โ€“40: Extremely rare.
40โ€“50: Elite wealth.
50โ€“60: Exceptionally wealthy.
60+: Massive legacy potential.

8. Ultra-High Net Worth โ€” $50Mโ€“$500M

You're now in the global wealth elite. Netflix movie tier rich. Rich to the point of having so much that you can't even spend it all alone. Rich enough to influence elections, change policies etc also.

Private aircraft, superyachts, multiple international properties and large private-company investments are financially accessible.

At this scale, ordinary consumption barely moves the balance sheet. To protect your wealth you need to operate like an institution. Offshore Holding Structures, Captive Insurance companies, Opportunity Zone funds around the globe. Lot of ways of avoiding taxes when you are this rich with good connections and a network

Goal: Preserve and compound capital, control major assets/businesses, institutionalize wealth and create lasting legacy.

Age verdict:

Under 40: You have basically broken the game. ๐Ÿ—ฟ
40โ€“50: Extremely exceptional.
50โ€“70: Elite global wealth.
70+: The question is now what happens to the wealth after you.

Note: $30M+ is commonly used as the industry UHNW threshold but I'm using $50M here to create a cleaner lifestyle tier.


9. Billionaire / Near-Billionaire โ€” $500Mโ€“$100B

$500M isn't technically billionaire territory hence the near-billionaire label. At $1B+, personal consumption is no longer the interesting part. You can't spend that money even if you want to on material assets. The important thing is ownership.

You may own a major corporation, enormous equity positions or businesses whose activities affect entire industries. Funnily enough at this tier of wealth your effective income tax rate is ironically lower than your assistant because net worths at this tier lives in unrealized stock/equity. Draw $1 salaries, take massive loans against equity, and dump large share blocks into Charitable Lead/Remainder Trusts (CLATs/CRUTs) and avoid taxes entirely but still have the ability to vote and have complete autonomy and power. Like the old saying goes it is very expensive to be poor

View attachment 5643186

Goal: Corporate control, capital allocation, global expansion, philanthropy and legacy.

Age verdict:

Under 40: You are an extreme statistical outlier.
40โ€“60: Usually the result of extraordinary entrepreneurship. Obviously extremely rich
60+: Still an extraordinarily rare level of wealth.

10. ๐Ÿ‘‘ Centibillionaire โ€” $100B+

This is another universe. At this point, the distinction between rich and extremely rich becomes almost meaningless. You're dealing with fortunes large enough that market fluctuations can change your net worth by $5B in a single afternoon. Can buy anything and everything possible.

You don't adapt to tax codes. Tax codes adapt to you. You have direct access to world leaders who are ready the lick the sole of your boots to appease your company and make you happy. You can directly negotiate custom sovereign level corporate tax just for you and so much more. you are practically an emperor in the modern world

Goal: Shape human progress, fund space programs, build AI networks, and influence geopolitical policy.

Age verdict:

Any age: ๐Ÿ—ฟ You're one of the wealthiest humans in recorded history.

You can adapt the above numbers for your country by multiplying the ranges with the PPP of your country to get a rough idea if you are not from the US


Also net worth is only one dimension.

Age + location + liquidity + income + spending = actual financial position.

Which tier are you in? Comment below.
i have like $1000 net worth i think including my PC and phone
 
  • +1
Reactions: sasha108, Jason Voorhees and Askinov
I have 700 bucks at 17, am i good?
 
  • +1
Reactions: Jason Voorhees and sasha108
@jgrey080 @Gudlifer @CloudyCuck
 
  • +1
Reactions: jgrey080 and sasha108
Net Worth Tiers โ€” 2026 Edition

I updated my old wealth-tier system for 2026. This time I'm accounting for inflation, housing costs, purchasing power, and the fact that $1M at 25 and $1M at 65 are two completely different situations.

1. ๐Ÿ’€ Debt-Bound โ€” < $0 NW

Your liabilities exceed your assets. Debt is eating into your income and you have little/no financial cushion and are dependent on your parents or someone directly. The government gives you zero love here. Consumer debts like credit cards, personal loans offers $0 in tax deductions. You are treated and are by all means a financial leper

Goal: Kill high-interest debt, establish liquidity and reach $0.

Honestly a terrible situation to be at any age unless you are in school but especially worse if you're approaching 20+ with substantial negative net worth.

2. Financially Struggling โ€” $0โ€“$65K

Positive net worth, but not much financial resilience. A job loss, medical emergency can bring you to the streets. You can't afford legal loopholes, so your best play is tax deferral and tax advantaged accounts of your country like Roth IRA, 401k etc. Claim the Saver's Match/Credit if eligible and other government schemes available

Goal: 3โ€“6 months emergency fund + start investing.

18โ€“25: Fine. You're just starting.
25โ€“35: Bad situation but okay start building aggressively
35โ€“45: Falling behind
45+: ๐Ÿšจ You have failed at life

3. Financially Stable โ€” $65Kโ€“$150K

You have manageable debt and consistent positive cash flow. No longer financially fragile, but you're still heavily dependent on employment. Your primary tax shield is maxing out tax advantaged accounts. More of them open to you since you are financially stable example for USA like HSA for and Backdoor Roth IRAs.

Goal: Build a substantial investment portfolio and start approaching true financial independence.

20โ€“25: Good
25โ€“35: Not bad
35โ€“45: Bad
45+: Failed at life

4. Core Middle Class โ€” $150Kโ€“$1.2M

In 2026. Comfortable or barely Millionaire is middle class in most US cities unless you live in middle of nowhere . It's simply a reality whether you want to accept it or not. Overall solid accumulated wealth. Can start a family have a retirement accounts, investments, home equity and other assets. Same strategy as tiers below but with a lot more leeway and investment potential. Also in the weird twilight zone of wealth too poor for loopholes,too rich for benefits. Also called the middle class squeeze

You can have a comfortable conventional lifestyle vacations, decent cars, homeownership but you're not financially bulletproof yet.

Goal: Build enough assets so you no longer need a job eventually

Age verdict:

20โ€“25: Very Good
25โ€“35: Good
35โ€“45: Decent
45โ€“50: Fine
55+: Okay but you still probably need more assets to retire.

5. Affluent / Upper-Middle โ€” $1.2Mโ€“$6M

You are a millionaire at $1M+, although $1.2M and $6M obviously produce very different lifestyles. In a low/mid-cost region financial independence can become realistic. In New York, London, San Francisco, Singapore and other expensive hubs the same money is pretty much middle class. The shift from ordinary income to capital gains begins now for harvesting long-term capital gains so you can do proper wealth building instead of fighting for scraps now

Goal: Transition from earning money to building assets and wealth to produce your lifestyle.

Age verdict:

20โ€“25: Baller
25โ€“35: Exceptional.
35โ€“45: Excellent.
45โ€“55: Great
55+: Wealthy, although retirement spending and asset liquidity matter.


6. High Net Worth โ€” $6Mโ€“$15M

Now we are talking about real wealth. You are in genuine financial independence territory. Can potentially generate a very substantial income from investments if you play your cards well. All the lucrative investment options open up. The biggest enemy at this tier and after this will be taxes so your priority would be to minimize the money you give to government. So after this tier it is a balancing act. You need to Master Buy, Borrow, Die. Borrow low-interest funds against portfolio lines of credit to fund lifestyle tax-free while going into exchanges to roll over real estate gains indefinitely.

Luxury housing, premium vehicles, international travel and expensive hobbies everything within reach

Goal: Optimize taxes this is the most important goal, Diversify and generate sustainable investment income and learn about tax loopholes, hedging and other grey area tactics

Age verdict:

20โ€“30: Filthy
30โ€“40: Exceptional
40โ€“50: Excellent.
50โ€“60: Very wealthy.
60+: You have substantial retirement/legacy wealth.


7. Very High Net Worth โ€” $15Mโ€“$50M

At this point your lifestyle is largely detached from employment. You are not the one getting a 6 figure salary you are the one paying people 6 figure salaries. Once again the biggest enemy is taxes, liabilities, policies. It is less about how do I earn more money and more of how do I protect the money I already have because taxes will rape your ass if you are not careful

Multiple homes, luxury vehicles, extensive international travel and substantial private market investments are all realistic.

At this tier. You should have a family office style wealth management and permanently employ people to move capital and make investments for you to protect your wealth. Hire specialised CPAs and attorneys to deploy Irrevocable Trusts to shield your millions from the IRS

Goal: Estate planning, asset protection, intergenerational wealth and capital allocation by employing a group of wealth managers and accountants.

Under 30: What the hell are you doing nigga
30โ€“40: Extremely rare.
40โ€“50: Elite wealth.
50โ€“60: Exceptionally wealthy.
60+: Massive legacy potential.

8. Ultra-High Net Worth โ€” $50Mโ€“$500M

You're now in the global wealth elite. Netflix movie tier rich. Rich to the point of having so much that you can't even spend it all alone. Rich enough to influence elections, change policies etc also.

Private aircraft, superyachts, multiple international properties and large private-company investments are financially accessible.

At this scale, ordinary consumption barely moves the balance sheet. To protect your wealth you need to operate like an institution. Offshore Holding Structures, Captive Insurance companies, Opportunity Zone funds around the globe. Lot of ways of avoiding taxes when you are this rich with good connections and a network

Goal: Preserve and compound capital, control major assets/businesses, institutionalize wealth and create lasting legacy.

Age verdict:

Under 40: You have basically broken the game. ๐Ÿ—ฟ
40โ€“50: Extremely exceptional.
50โ€“70: Elite global wealth.
70+: The question is now what happens to the wealth after you.

Note: $30M+ is commonly used as the industry UHNW threshold but I'm using $50M here to create a cleaner lifestyle tier.


9. Billionaire / Near-Billionaire โ€” $500Mโ€“$100B

$500M isn't technically billionaire territory hence the near-billionaire label. At $1B+, personal consumption is no longer the interesting part. You can't spend that money even if you want to on material assets. The important thing is ownership.

You may own a major corporation, enormous equity positions or businesses whose activities affect entire industries. Funnily enough at this tier of wealth your effective income tax rate is ironically lower than your assistant because net worths at this tier lives in unrealized stock/equity. Draw $1 salaries, take massive loans against equity, and dump large share blocks into Charitable Lead/Remainder Trusts (CLATs/CRUTs) and avoid taxes entirely but still have the ability to vote and have complete autonomy and power. Like the old saying goes it is very expensive to be poor

View attachment 5643186

Goal: Corporate control, capital allocation, global expansion, philanthropy and legacy.

Age verdict:

Under 40: You are an extreme statistical outlier.
40โ€“60: Usually the result of extraordinary entrepreneurship. Obviously extremely rich
60+: Still an extraordinarily rare level of wealth.

10. ๐Ÿ‘‘ Centibillionaire โ€” $100B+

This is another universe. At this point, the distinction between rich and extremely rich becomes almost meaningless. You're dealing with fortunes large enough that market fluctuations can change your net worth by $5B in a single afternoon. Can buy anything and everything possible.

You don't adapt to tax codes. Tax codes adapt to you. You have direct access to world leaders who are ready the lick the sole of your boots to appease your company and make you happy. You can directly negotiate custom sovereign level corporate tax just for you and so much more. you are practically an emperor in the modern world

Goal: Shape human progress, fund space programs, build AI networks, and influence geopolitical policy.

Age verdict:

Any age: ๐Ÿ—ฟ You're one of the wealthiest humans in recorded history.

You can adapt the above numbers for your country by multiplying the ranges with the PPP of your country to get a rough idea if you are not from the US


Also net worth is only one dimension.

Age + location + liquidity + income + spending = actual financial position.

Which tier are you in? Comment below.
Sorry my bad Iโ€™m only 16 ๐Ÿ˜•
 
  • +1
Reactions: Jason Voorhees
Net Worth Tiers โ€” 2026 Edition

I updated my old wealth-tier system for 2026. This time I'm accounting for inflation, housing costs, purchasing power, and the fact that $1M at 25 and $1M at 65 are two completely different situations.

1. ๐Ÿ’€ Debt-Bound โ€” < $0 NW

Your liabilities exceed your assets. Debt is eating into your income and you have little/no financial cushion and are dependent on your parents or someone directly. The government gives you zero love here. Consumer debts like credit cards, personal loans offers $0 in tax deductions. You are treated and are by all means a financial leper

Goal: Kill high-interest debt, establish liquidity and reach $0.

Honestly a terrible situation to be at any age unless you are in school but especially worse if you're approaching 20+ with substantial negative net worth.

2. Financially Struggling โ€” $0โ€“$65K

Positive net worth, but not much financial resilience. A job loss, medical emergency can bring you to the streets. You can't afford legal loopholes, so your best play is tax deferral and tax advantaged accounts of your country like Roth IRA, 401k etc. Claim the Saver's Match/Credit if eligible and other government schemes available

Goal: 3โ€“6 months emergency fund + start investing.

18โ€“25: Fine. You're just starting.
25โ€“35: Bad situation but okay start building aggressively
35โ€“45: Falling behind
45+: ๐Ÿšจ You have failed at life

3. Financially Stable โ€” $65Kโ€“$150K

You have manageable debt and consistent positive cash flow. No longer financially fragile, but you're still heavily dependent on employment. Your primary tax shield is maxing out tax advantaged accounts. More of them open to you since you are financially stable example for USA like HSA for and Backdoor Roth IRAs.

Goal: Build a substantial investment portfolio and start approaching true financial independence.

20โ€“25: Good
25โ€“35: Not bad
35โ€“45: Bad
45+: Failed at life

4. Core Middle Class โ€” $150Kโ€“$1.2M

In 2026. Comfortable or barely Millionaire is middle class in most US cities unless you live in middle of nowhere . It's simply a reality whether you want to accept it or not. Overall solid accumulated wealth. Can start a family have a retirement accounts, investments, home equity and other assets. Same strategy as tiers below but with a lot more leeway and investment potential. Also in the weird twilight zone of wealth too poor for loopholes,too rich for benefits. Also called the middle class squeeze

You can have a comfortable conventional lifestyle vacations, decent cars, homeownership but you're not financially bulletproof yet.

Goal: Build enough assets so you no longer need a job eventually

Age verdict:

20โ€“25: Very Good
25โ€“35: Good
35โ€“45: Decent
45โ€“50: Fine
55+: Okay but you still probably need more assets to retire.

5. Affluent / Upper-Middle โ€” $1.2Mโ€“$6M

You are a millionaire at $1M+, although $1.2M and $6M obviously produce very different lifestyles. In a low/mid-cost region financial independence can become realistic. In New York, London, San Francisco, Singapore and other expensive hubs the same money is pretty much middle class. The shift from ordinary income to capital gains begins now for harvesting long-term capital gains so you can do proper wealth building instead of fighting for scraps now

Goal: Transition from earning money to building assets and wealth to produce your lifestyle.

Age verdict:

20โ€“25: Baller
25โ€“35: Exceptional.
35โ€“45: Excellent.
45โ€“55: Great
55+: Wealthy, although retirement spending and asset liquidity matter.


6. High Net Worth โ€” $6Mโ€“$15M

Now we are talking about real wealth. You are in genuine financial independence territory. Can potentially generate a very substantial income from investments if you play your cards well. All the lucrative investment options open up. The biggest enemy at this tier and after this will be taxes so your priority would be to minimize the money you give to government. So after this tier it is a balancing act. You need to Master Buy, Borrow, Die. Borrow low-interest funds against portfolio lines of credit to fund lifestyle tax-free while going into exchanges to roll over real estate gains indefinitely.

Luxury housing, premium vehicles, international travel and expensive hobbies everything within reach

Goal: Optimize taxes this is the most important goal, Diversify and generate sustainable investment income and learn about tax loopholes, hedging and other grey area tactics

Age verdict:

20โ€“30: Filthy
30โ€“40: Exceptional
40โ€“50: Excellent.
50โ€“60: Very wealthy.
60+: You have substantial retirement/legacy wealth.


7. Very High Net Worth โ€” $15Mโ€“$50M

At this point your lifestyle is largely detached from employment. You are not the one getting a 6 figure salary you are the one paying people 6 figure salaries. Once again the biggest enemy is taxes, liabilities, policies. It is less about how do I earn more money and more of how do I protect the money I already have because taxes will rape your ass if you are not careful

Multiple homes, luxury vehicles, extensive international travel and substantial private market investments are all realistic.

At this tier. You should have a family office style wealth management and permanently employ people to move capital and make investments for you to protect your wealth. Hire specialised CPAs and attorneys to deploy Irrevocable Trusts to shield your millions from the IRS

Goal: Estate planning, asset protection, intergenerational wealth and capital allocation by employing a group of wealth managers and accountants.

Under 30: What the hell are you doing nigga
30โ€“40: Extremely rare.
40โ€“50: Elite wealth.
50โ€“60: Exceptionally wealthy.
60+: Massive legacy potential.

8. Ultra-High Net Worth โ€” $50Mโ€“$500M

You're now in the global wealth elite. Netflix movie tier rich. Rich to the point of having so much that you can't even spend it all alone. Rich enough to influence elections, change policies etc also.

Private aircraft, superyachts, multiple international properties and large private-company investments are financially accessible.

At this scale, ordinary consumption barely moves the balance sheet. To protect your wealth you need to operate like an institution. Offshore Holding Structures, Captive Insurance companies, Opportunity Zone funds around the globe. Lot of ways of avoiding taxes when you are this rich with good connections and a network

Goal: Preserve and compound capital, control major assets/businesses, institutionalize wealth and create lasting legacy.

Age verdict:

Under 40: You have basically broken the game. ๐Ÿ—ฟ
40โ€“50: Extremely exceptional.
50โ€“70: Elite global wealth.
70+: The question is now what happens to the wealth after you.

Note: $30M+ is commonly used as the industry UHNW threshold but I'm using $50M here to create a cleaner lifestyle tier.


9. Billionaire / Near-Billionaire โ€” $500Mโ€“$100B

$500M isn't technically billionaire territory hence the near-billionaire label. At $1B+, personal consumption is no longer the interesting part. You can't spend that money even if you want to on material assets. The important thing is ownership.

You may own a major corporation, enormous equity positions or businesses whose activities affect entire industries. Funnily enough at this tier of wealth your effective income tax rate is ironically lower than your assistant because net worths at this tier lives in unrealized stock/equity. Draw $1 salaries, take massive loans against equity, and dump large share blocks into Charitable Lead/Remainder Trusts (CLATs/CRUTs) and avoid taxes entirely but still have the ability to vote and have complete autonomy and power. Like the old saying goes it is very expensive to be poor

View attachment 5643186

Goal: Corporate control, capital allocation, global expansion, philanthropy and legacy.

Age verdict:

Under 40: You are an extreme statistical outlier.
40โ€“60: Usually the result of extraordinary entrepreneurship. Obviously extremely rich
60+: Still an extraordinarily rare level of wealth.

10. ๐Ÿ‘‘ Centibillionaire โ€” $100B+

This is another universe. At this point, the distinction between rich and extremely rich becomes almost meaningless. You're dealing with fortunes large enough that market fluctuations can change your net worth by $5B in a single afternoon. Can buy anything and everything possible.

You don't adapt to tax codes. Tax codes adapt to you. You have direct access to world leaders who are ready the lick the sole of your boots to appease your company and make you happy. You can directly negotiate custom sovereign level corporate tax just for you and so much more. you are practically an emperor in the modern world

Goal: Shape human progress, fund space programs, build AI networks, and influence geopolitical policy.

Age verdict:

Any age: ๐Ÿ—ฟ You're one of the wealthiest humans in recorded history.

You can adapt the above numbers for your country by multiplying the ranges with the PPP of your country to get a rough idea if you are not from the US


Also net worth is only one dimension.

Age + location + liquidity + income + spending = actual financial position.

Which tier are you in? Comment below.
Im 19,so basically 2. Im still working and studying
Im not sure about net worth tho, maybe few thousand
 
  • +1
Reactions: BigBallsLarry and Jason Voorhees
@Sayori @swedchud @socio
 
  • +1
Reactions: Sayori
blud is just posting AI stuff now
 
  • +1
Reactions: ร˜UROBOROS and Jason Voorhees
@Whatever @PeenoResurrected
 
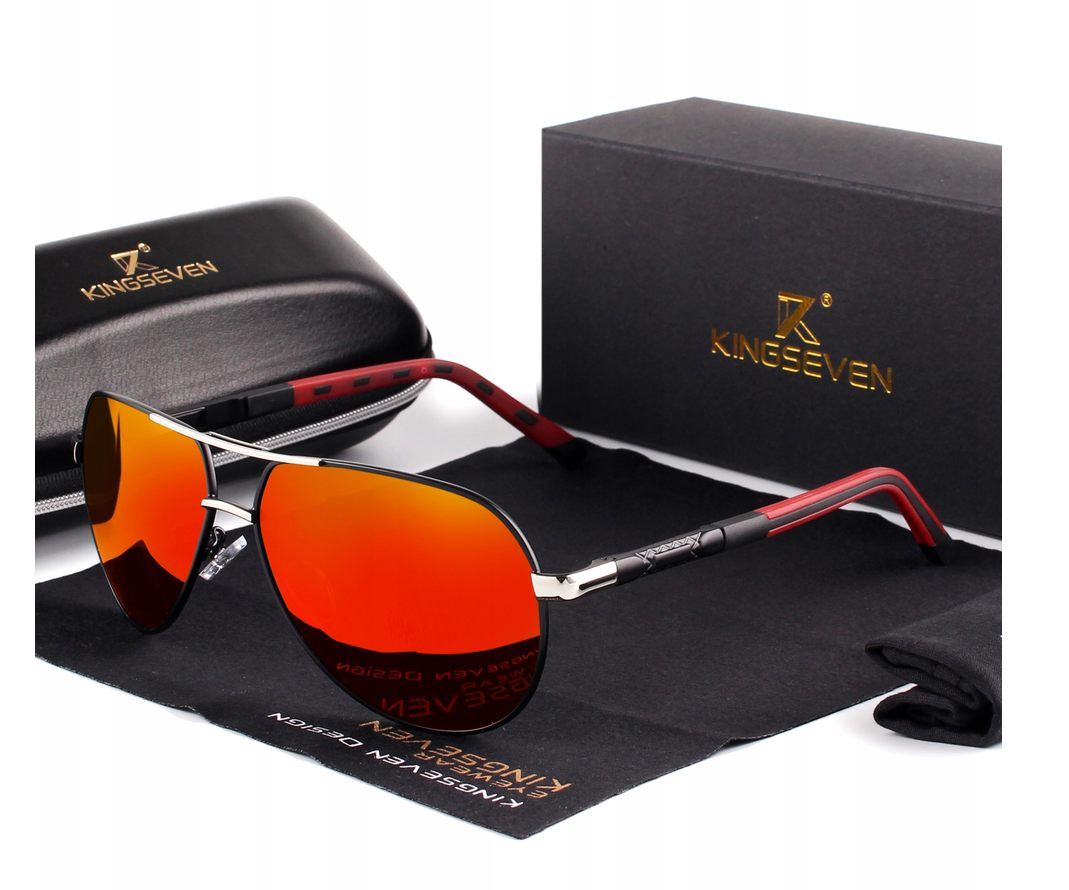
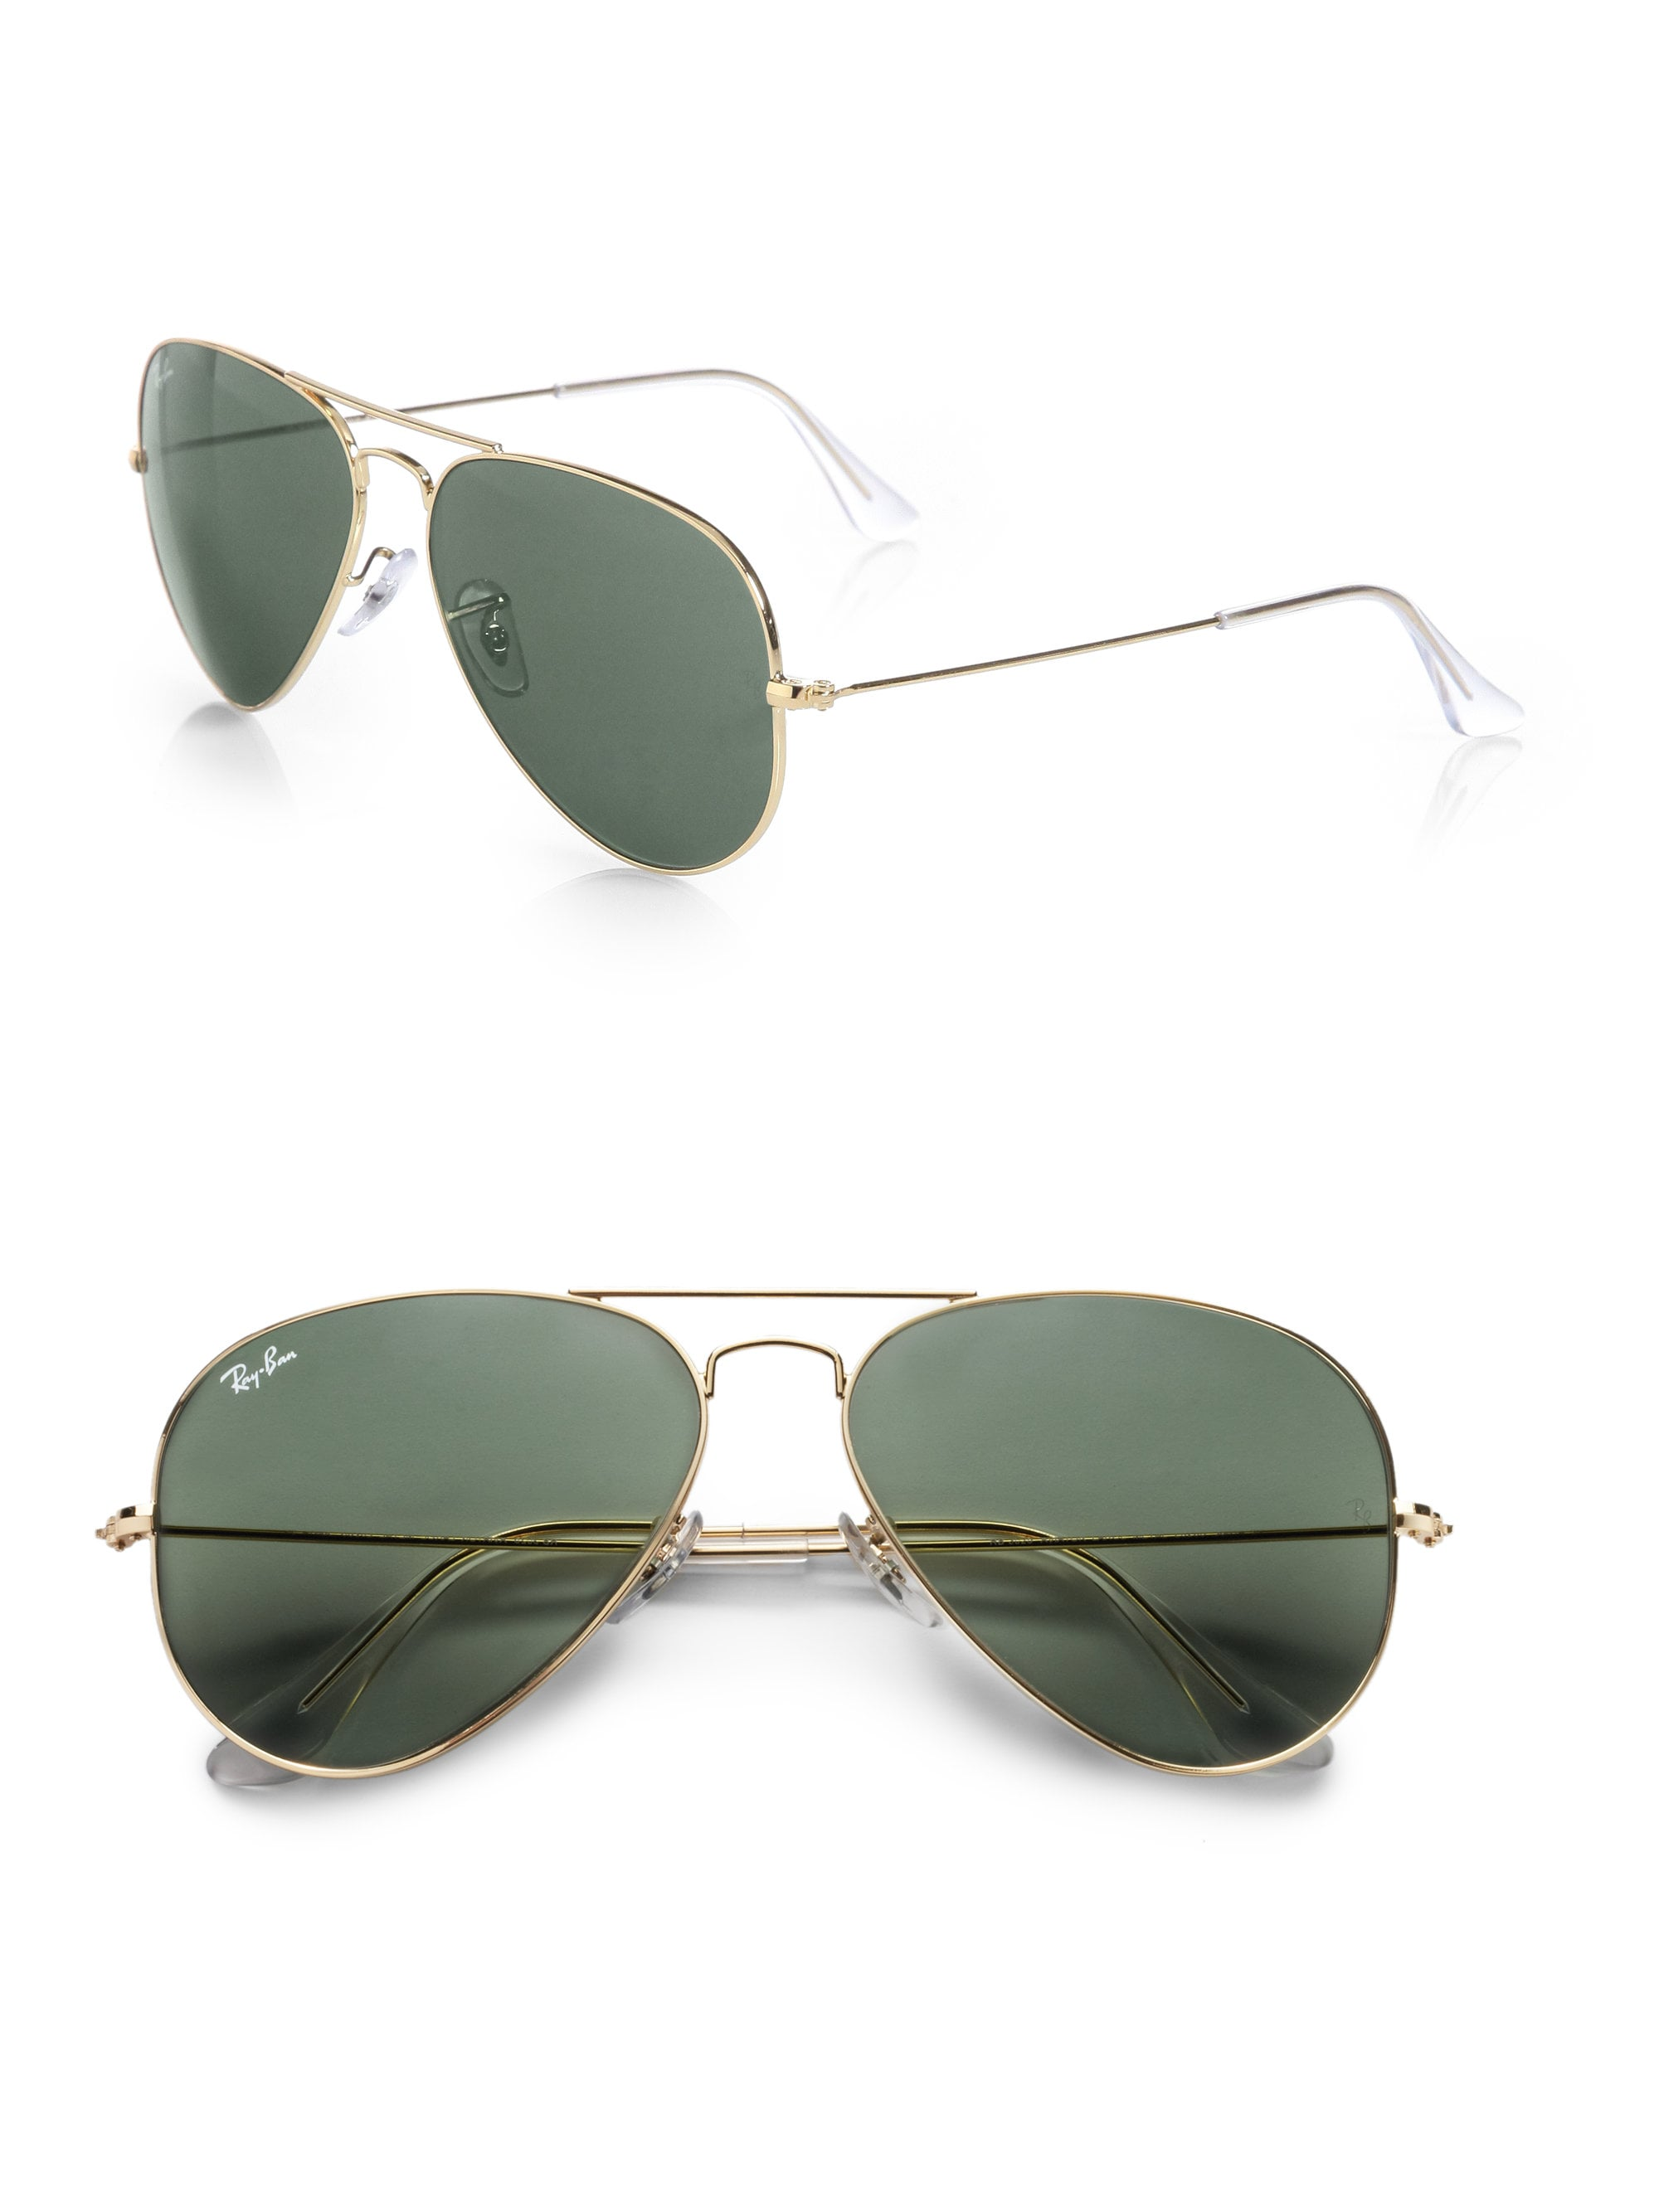
@Jason Voorhees rate the sunglasses

1.
1789377664494

2.
1789377696728


first is cheap option second is expensive option
 
  • +1
  • Love it
Reactions: Jason Voorhees and hopelessmanlet32
Wtf
What is per hour?
I have free schedule, the most money i got is 400+ bucks in one week (54+ hours)
around 4 bucks per hour
 
  • +1
Reactions: sasha108 and Jason Voorhees
i have 20 bucks at 15 me rich boi
 
  • +1
Reactions: Jason Voorhees
  • +1
Reactions: sasha108, zennn and hopelessmanlet32
Wtf
What is per hour?
I have free schedule, the most money i got is 400+ bucks in one week (54+ hours)
i get round about 1,50โ‚ฌ per hour but its because i work at an workshop for the disabled
 
  • +1
Reactions: sasha108 and Jason Voorhees
  • +1
Reactions: sasha108, BigBallsLarry and hopelessmanlet32
  • +1
Reactions: hopelessmanlet32 and Jason Voorhees
  • +1
Reactions: hopelessmanlet32
  • +1
Reactions: BigBallsLarry
  • +1
Reactions: Jason Voorhees
@eduardkoopman @Seth Walsh
 
  • +1
Reactions: Seth Walsh
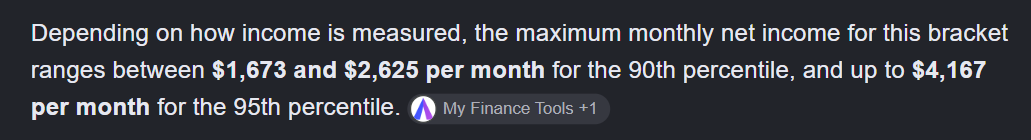
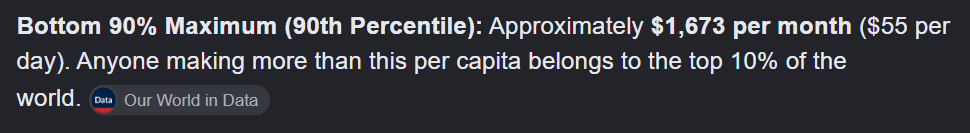
95% of the world's population makes under 50k, so we're kind fucked I guess.. :veryCat:

1789377779170

1789377794789
 
Last edited:
  • +1
  • Hmm...
Reactions: sasha108 and Jason Voorhees
Net Worth Tiers โ€” 2026 Edition

I updated my old wealth-tier system for 2026. This time I'm accounting for inflation, housing costs, purchasing power, and the fact that $1M at 25 and $1M at 65 are two completely different situations.

1. ๐Ÿ’€ Debt-Bound โ€” < $0 NW

Your liabilities exceed your assets. Debt is eating into your income and you have little/no financial cushion and are dependent on your parents or someone directly. The government gives you zero love here. Consumer debts like credit cards, personal loans offers $0 in tax deductions. You are treated and are by all means a financial leper

Goal: Kill high-interest debt, establish liquidity and reach $0.

Honestly a terrible situation to be at any age unless you are in school but especially worse if you're approaching 20+ with substantial negative net worth.

2. Financially Struggling โ€” $0โ€“$65K

Positive net worth, but not much financial resilience. A job loss, medical emergency can bring you to the streets. You can't afford legal loopholes, so your best play is tax deferral and tax advantaged accounts of your country like Roth IRA, 401k etc. Claim the Saver's Match/Credit if eligible and other government schemes available

Goal: 3โ€“6 months emergency fund + start investing.

18โ€“25: Fine. You're just starting.
25โ€“35: Bad situation but okay start building aggressively
35โ€“45: Falling behind
45+: ๐Ÿšจ You have failed at life

3. Financially Stable โ€” $65Kโ€“$150K

You have manageable debt and consistent positive cash flow. No longer financially fragile, but you're still heavily dependent on employment. Your primary tax shield is maxing out tax advantaged accounts. More of them open to you since you are financially stable example for USA like HSA for and Backdoor Roth IRAs.

Goal: Build a substantial investment portfolio and start approaching true financial independence.

20โ€“25: Good
25โ€“35: Not bad
35โ€“45: Bad
45+: Failed at life

4. Core Middle Class โ€” $150Kโ€“$1.2M

In 2026. Comfortable or barely Millionaire is middle class in most US cities unless you live in middle of nowhere . It's simply a reality whether you want to accept it or not. Overall solid accumulated wealth. Can start a family have a retirement accounts, investments, home equity and other assets. Same strategy as tiers below but with a lot more leeway and investment potential. Also in the weird twilight zone of wealth too poor for loopholes,too rich for benefits. Also called the middle class squeeze

You can have a comfortable conventional lifestyle vacations, decent cars, homeownership but you're not financially bulletproof yet.

Goal: Build enough assets so you no longer need a job eventually

Age verdict:

20โ€“25: Very Good
25โ€“35: Good
35โ€“45: Decent
45โ€“50: Fine
55+: Okay but you still probably need more assets to retire.

5. Affluent / Upper-Middle โ€” $1.2Mโ€“$6M

You are a millionaire at $1M+, although $1.2M and $6M obviously produce very different lifestyles. In a low/mid-cost region financial independence can become realistic. In New York, London, San Francisco, Singapore and other expensive hubs the same money is pretty much middle class. The shift from ordinary income to capital gains begins now for harvesting long-term capital gains so you can do proper wealth building instead of fighting for scraps now

Goal: Transition from earning money to building assets and wealth to produce your lifestyle.

Age verdict:

20โ€“25: Baller
25โ€“35: Exceptional.
35โ€“45: Excellent.
45โ€“55: Great
55+: Wealthy, although retirement spending and asset liquidity matter.


6. High Net Worth โ€” $6Mโ€“$15M

Now we are talking about real wealth. You are in genuine financial independence territory. Can potentially generate a very substantial income from investments if you play your cards well. All the lucrative investment options open up. The biggest enemy at this tier and after this will be taxes so your priority would be to minimize the money you give to government. So after this tier it is a balancing act. You need to Master Buy, Borrow, Die. Borrow low-interest funds against portfolio lines of credit to fund lifestyle tax-free while going into exchanges to roll over real estate gains indefinitely.

Luxury housing, premium vehicles, international travel and expensive hobbies everything within reach

Goal: Optimize taxes this is the most important goal, Diversify and generate sustainable investment income and learn about tax loopholes, hedging and other grey area tactics

Age verdict:

20โ€“30: Filthy
30โ€“40: Exceptional
40โ€“50: Excellent.
50โ€“60: Very wealthy.
60+: You have substantial retirement/legacy wealth.


7. Very High Net Worth โ€” $15Mโ€“$50M

At this point your lifestyle is largely detached from employment. You are not the one getting a 6 figure salary you are the one paying people 6 figure salaries. Once again the biggest enemy is taxes, liabilities, policies. It is less about how do I earn more money and more of how do I protect the money I already have because taxes will rape your ass if you are not careful

Multiple homes, luxury vehicles, extensive international travel and substantial private market investments are all realistic.

At this tier. You should have a family office style wealth management and permanently employ people to move capital and make investments for you to protect your wealth. Hire specialised CPAs and attorneys to deploy Irrevocable Trusts to shield your millions from the IRS

Goal: Estate planning, asset protection, intergenerational wealth and capital allocation by employing a group of wealth managers and accountants.

Under 30: What the hell are you doing nigga
30โ€“40: Extremely rare.
40โ€“50: Elite wealth.
50โ€“60: Exceptionally wealthy.
60+: Massive legacy potential.

8. Ultra-High Net Worth โ€” $50Mโ€“$500M

You're now in the global wealth elite. Netflix movie tier rich. Rich to the point of having so much that you can't even spend it all alone. Rich enough to influence elections, change policies etc also.

Private aircraft, superyachts, multiple international properties and large private-company investments are financially accessible.

At this scale, ordinary consumption barely moves the balance sheet. To protect your wealth you need to operate like an institution. Offshore Holding Structures, Captive Insurance companies, Opportunity Zone funds around the globe. Lot of ways of avoiding taxes when you are this rich with good connections and a network

Goal: Preserve and compound capital, control major assets/businesses, institutionalize wealth and create lasting legacy.

Age verdict:

Under 40: You have basically broken the game. ๐Ÿ—ฟ
40โ€“50: Extremely exceptional.
50โ€“70: Elite global wealth.
70+: The question is now what happens to the wealth after you.

Note: $30M+ is commonly used as the industry UHNW threshold but I'm using $50M here to create a cleaner lifestyle tier.


9. Billionaire / Near-Billionaire โ€” $500Mโ€“$100B

$500M isn't technically billionaire territory hence the near-billionaire label. At $1B+, personal consumption is no longer the interesting part. You can't spend that money even if you want to on material assets. The important thing is ownership.

You may own a major corporation, enormous equity positions or businesses whose activities affect entire industries. Funnily enough at this tier of wealth your effective income tax rate is ironically lower than your assistant because net worths at this tier lives in unrealized stock/equity. Draw $1 salaries, take massive loans against equity, and dump large share blocks into Charitable Lead/Remainder Trusts (CLATs/CRUTs) and avoid taxes entirely but still have the ability to vote and have complete autonomy and power. Like the old saying goes it is very expensive to be poor

View attachment 5643186

Goal: Corporate control, capital allocation, global expansion, philanthropy and legacy.

Age verdict:

Under 40: You are an extreme statistical outlier.
40โ€“60: Usually the result of extraordinary entrepreneurship. Obviously extremely rich
60+: Still an extraordinarily rare level of wealth.

10. ๐Ÿ‘‘ Centibillionaire โ€” $100B+

This is another universe. At this point, the distinction between rich and extremely rich becomes almost meaningless. You're dealing with fortunes large enough that market fluctuations can change your net worth by $5B in a single afternoon. Can buy anything and everything possible.

You don't adapt to tax codes. Tax codes adapt to you. You have direct access to world leaders who are ready the lick the sole of your boots to appease your company and make you happy. You can directly negotiate custom sovereign level corporate tax just for you and so much more. you are practically an emperor in the modern world

Goal: Shape human progress, fund space programs, build AI networks, and influence geopolitical policy.

Age verdict:

Any age: ๐Ÿ—ฟ You're one of the wealthiest humans in recorded history.

You can adapt the above numbers for your country by multiplying the ranges with the PPP of your country to get a rough idea if you are not from the US


Also net worth is only one dimension.

Age + location + liquidity + income + spending = actual financial position.

Which tier are you in? Comment below.
Good post.
I am at the stage where i own nothing. You read out loud with me IRS? NOTHING
 
  • +1
Reactions: Jason Voorhees
@Thief @DildoFaggins @Foreverbrad
 
@eduardkoopman @Seth Walsh
The biggest trap is looking at it like a snapshot.


Most people treat wealth as
โ€œHow rich are you today?โ€


But the main thing is protecting the GENERATOR. Your ability to get paid, and your ability to keep buying more productive assets while keeping yourself insulated from forcing/coercing constraints. i.e., having liquid buffer for shocks, controlling fixed costs, recurring expenses etc.

So the best sort of question is:
โ€œWhat happens to your system after 1,000 possible bad sequencesโ€”and in how many of them are you still alive, still invested, and still compounding?โ€
 
  • +1
Reactions: Bully and Jason Voorhees
The biggest trap is looking at it like a snapshot.


Most people treat wealth as


But the main thing is protecting the GENERATOR. Your ability to get paid, and your ability to keep buying more productive assets while keeping yourself insulated from forcing/coercing constraints. i.e., having liquid buffer for shocks, controlling fixed costs, recurring expenses etc.

So the best sort of question is:
I think the most underrated thing in wealth building is the fact that those who haven't engineered their positioning to NOT get forced out of the game by repeated unexpected bad shocks; actually do get forced out. And after they go bust, it's a complete state change. They're forgotten about and learn an expensive lesson.

The winners are those who first make themselves robust to bad sequences, leave enough slack for real life uncertainty, and compound over long durations (decades and decades), without obsessing over "outcompeting" someone else, or some benchmark.

What matters is staying in the game and compounding meaningfully. Some people get away with using debt strategically to finance assets they don't yet own, because they're modelling the downside and pooled risks; using debt is still riskier, but they understand that owning more assets is essentially owning more wealth.

The patient, however, win.
 
Last edited:
  • +1
Reactions: SecularIslamist and Jason Voorhees
I wouldnโ€™t expect many people on this forum to be above the second tier.
 
  • +1
  • Hmm...
Reactions: Jason Voorhees and sasha108

Similar threads

Blondepawg'sDildo
Replies
5
Views
82
Junbae
Junbae
inversions
Replies
4
Views
64
inversions
inversions
lockhead
Replies
0
Views
13
lockhead
lockhead
tension
Replies
7
Views
42
britadeirajunior999
britadeirajunior999
ANON
Replies
40
Views
231
EternalGreydom
EternalGreydom

Users who are viewing this thread

  • HispanicMogger
  • ร˜UROBOROS
  • trvechud
  • loneiqlet
  • bigfatuglyc6nt
  • 0ogrpostcel
Back
Top